Group Management Report
Output volume and revenue
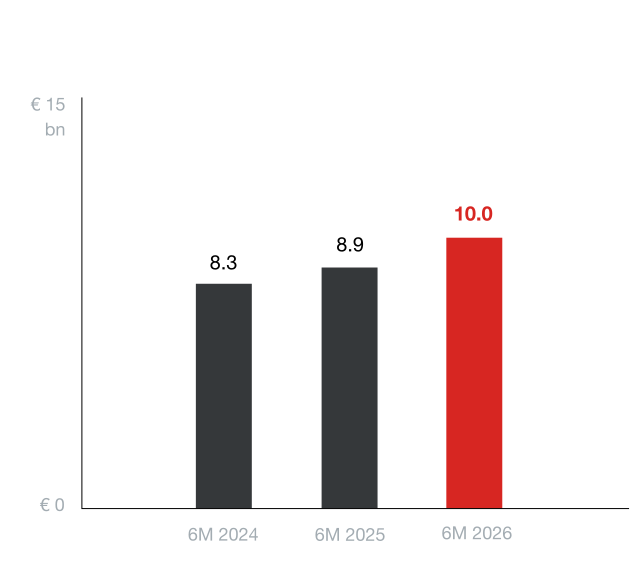
STRABAG SE increased its output volume significantly in the first half of 2026 with a plus of 12% to € 9,982.67 million. While transportation infrastructure projects started later in the first quarter due to prolonged periods of cold weather in Europe, output rose strongly in the second quarter. The largest increase was recorded in Germany, particularly in energy infrastructure and railway construction. Significant growth in output volume was also achieved in the United Kingdom, partly as a result of the acquisition of Van Elle, as well as in the Czech Republic and Croatia.
Consolidated revenue increased by 15%, slightly faster than output. As a result, the ratio of revenue to output rose from 89% to 92% year on year.
Order backlog
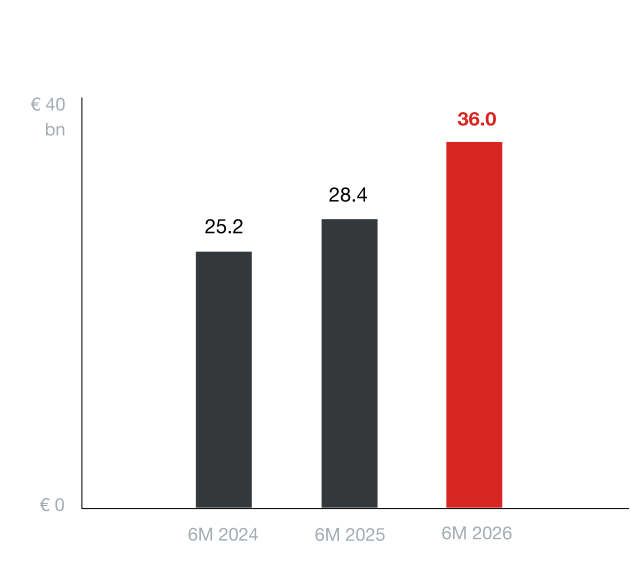
STRABAG SE’s order backlog once again grew substantially in the first half of 2026, reaching € 35,985.22 million as at 30 June 2026. This represents an increase of 27% compared with the same date in the previous year and 15% compared with year-end 2025. The largest increases in the first half of 2026 were recorded in Germany, the Americas, Australia, Austria and the core markets of Eastern Europe, particularly Poland and the Czech Republic.
Major orders received in the first half of 2026 included large-scale infrastructure contracts in Germany, among them several contract packages for the construction of the Pfaffensteig Tunnel, the replacement new build of the Erlangen lock and, in railway construction, the general refurbishment of the Lehrte–Oebisfelde section of the Hanover–Berlin high-speed line. Mining contracts worth around € 800 million contributed to the order backlog in Chile, while major railway construction contracts worth approximately € 490 million were secured in Australia. In Austria, notable orders included residential construction and energy infrastructure projects, while large-scale mobility infrastructure contracts were won in Eastern Europe.
Output volume
Order backlog
Financial performance
Earnings before interest, taxes, depreciation and amortisation (EBITDA) increased by 30% to € 560.09 million in the first half of 2026. Despite the higher revenue, the combined share of expenses for materials and services and employee benefits expense in revenue was reduced from 93% to 92%. Depreciation of property, plant and equipment and amortisation of intangible assets increased year on year to € 385.66 million (6M/2025: € 301.44 million). Unlike in the previous year, this figure includes a € 50 million impairment loss on goodwill in connection with an acquisition. Earnings before interest and taxes (EBIT) increased significantly by 35% to € 174.43 million.
The North + West segment achieved a significant improvement in earnings from an already high level. Earnings in the South + East segment remained negative in the first half of the year due to the higher proportion of transportation infrastructure projects; despite the colder weather in the first quarter, however, this figure was less negative than in the previous year. The International + Special Divisions segment delivered a solid earnings contribution despite the impact of the aforementioned impairment loss on goodwill.
Net interest income increased to € 29.43 million, compared with € 15.38 million in the first half of 2025. While net interest income in the previous year was adversely affected by exchange rate differences of € -13.04 million, these had virtually no impact in the reporting period, amounting to € 0.1 million. In addition, the higher level of liquidity compared with the previous year resulted in higher interest income. Earnings before taxes (EBT) therefore amounted to € 203.86 million, significantly above the previous year’s figure of € 144.75 million. Income tax expense came to € -83.99 million (6M/2025: € -47.68 million), increasing the effective income tax rate to 41%. The year-on-year increase was primarily attributable to the aforementioned impairment loss on goodwill, which is not deductible for tax purposes. This resulted in net income of € 119.87 million, compared with € 97.07 million in the first half of 2025.
The earnings attributable to non-controlling interests amounted to € 0.81 million and were therefore at a similar level to the previous year in absolute terms. Overall, net income after minorities amounted to € 119.06 million (6M/2025: € 94.89 million). Based on a weighted average of 115,442,696 shares outstanding in the first half of 2026, earnings per share amounted to € 1.03 (6M/2025: € 0.82).
Financial position and cash flows
The balance sheet total (total assets) amounted to € 16.8 billion as at 30 June 2026, 6% above the figure at year-end 2025. The main changes on the assets side resulted from the seasonal increase in inventories and contract assets, which was accompanied by a decline in cash and cash equivalents.
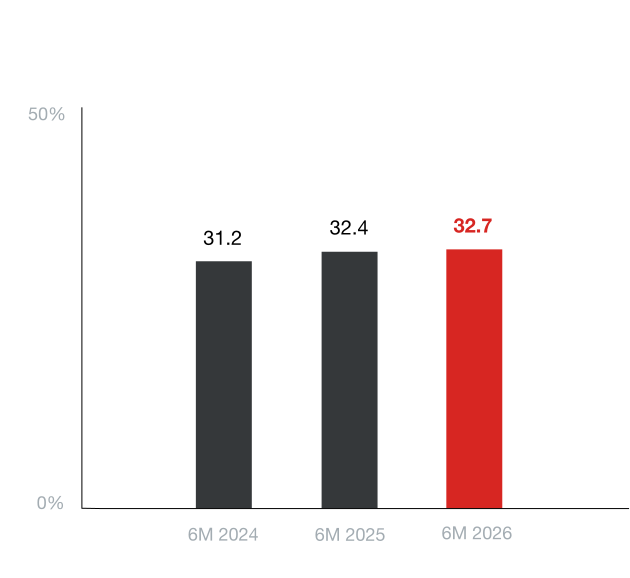
Compared with year-end 2025, the equity ratio decreased to 32.7% but remained at a high level (31 December 2025: 35.9%). This development was primarily attributable to the payment of the dividend for the 2025 financial year in the first half of 2026.
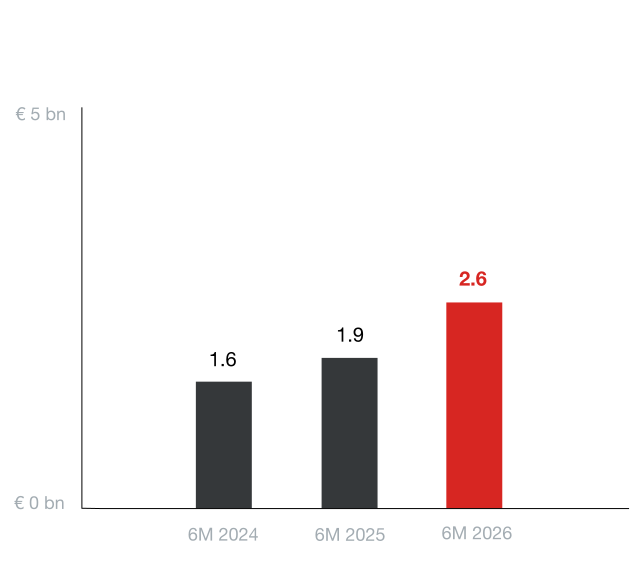
STRABAG continues to report a solid net cash position. Compared with year-end 2025, this decreased from € 3,518.26 million to € 2,606.26 million due to the seasonality typical of the construction business and the associated build-up of working capital, as well as investments made in the first half of the year.
Equity ratio
Net cash position
Cash flow from operating activities returned to positive territory at € 11.16 million (6M/2025: € -284.44 million). This development was attributable to higher cash flow from earnings as well as a smaller year-on-year build-up of working capital.
Cash flow from investing activities amounted to € -677.99 million (6M/2025: € -430.31 million). The higher cash outflow compared with the previous year is in line with the implementation of Strategy 2030 and was primarily attributable to the acquisitions of WTE, Van Elle and Stumpp Group.
Cash flow from financing activities amounted to € -245.07 million in the first half of 2026 (6M/2025: € -261.75 million). The cash outflow was therefore lower despite a higher dividend payment compared with the previous year. This was primarily due to the raising of non-recourse liabilities to refinance the expansion of the Hold Estate portfolio.
Capital expenditures
Capital expenditures focused on new machinery for infrastructure construction in Germany. In addition to maintenance expenditures for the broad-based regional business, investments were made primarily in additional railway construction machinery. Additional investments were also made for the execution of large-scale mining contracts in Chile. Regionally, major investments were concentrated primarily in the Czech Republic, Austria, Poland, Australia and Romania. The modernisation of construction materials facilities remains a key focus. The capital expenditures include € 360.38 million (6M/2025: € 349.13 million) for the acquisition of intangible assets, property, plant and equipment, and investment property – excluding non-cash additions to right-of-use assets from leases – as well as € 36.00 million (6M/2025: € 20.77 million) for the acquisition of financial assets and € 340.31 million (6M/2025: € 119.05 million) relating to changes in the scope of consolidation.
Employees
STRABAG had an average of 80,923 employees (FTE) in the first half of 2026, an increase of 2% compared to the same period of the previous year. The largest increases resulted from the acquisitions of Van Elle and the WTE Group as well as from the expansion of capacity to execute major projects in the United Kingdom and Germany. In the Americas, the number of employees declined as major projects progressed towards completion.
Major transactions, risks and strategy
During the first six months of the financial year, there were no transactions with related parties which significantly influenced the financial situation or the business result nor were there any changes to transactions with related parties which were presented in the annual financial statements of 31 December 2025 and which significantly influenced the financial situation or business result of the first six months of the current financial year.
In the course of its entrepreneurial activities, the STRABAG Group is exposed to a number of risks, which can be identified and assessed using an active risk management system and dealt with by applying an appropriate risk policy. Among the most important risks are external risks such as cyclical fluctuations in the construction industry, operating and technical risks in the selection and execution of projects, IT risks, investment risks as well as financial, personnel, ethical, legal and political risks. Additional risks exist with regard to work safety, environmental protection, quality, business continuity and supply chain.
The risks are explained in more detail in the 2025 management report. A review of the current risk situation revealed that in the reporting period there existed no risks which threatened the existence of the company and that for the future no risks are recognisable which constitute a threat to its continued existence.
In the first half of 2026, there were no significant changes to the Group strategy as detailed in the 2025 Annual and Sustainability Report.
Outlook
Based on the continued strong growth in the order backlog and the significant increase in output in the second quarter, the Management Board has updated its outlook for the 2026 financial year. It now expects output volume to approach € 23 billion, compared with the previous estimate of around € 22 billion. In view of the positive earnings development in the first half of the year, the EBIT margin for the full year 2026 is now expected to be between 5.5% and 6%, compared with the original forecast of between 5% and 5.5%. Net investments, defined as cash flow from investing activities, are still expected to amount to no more than € 1.5 billion.